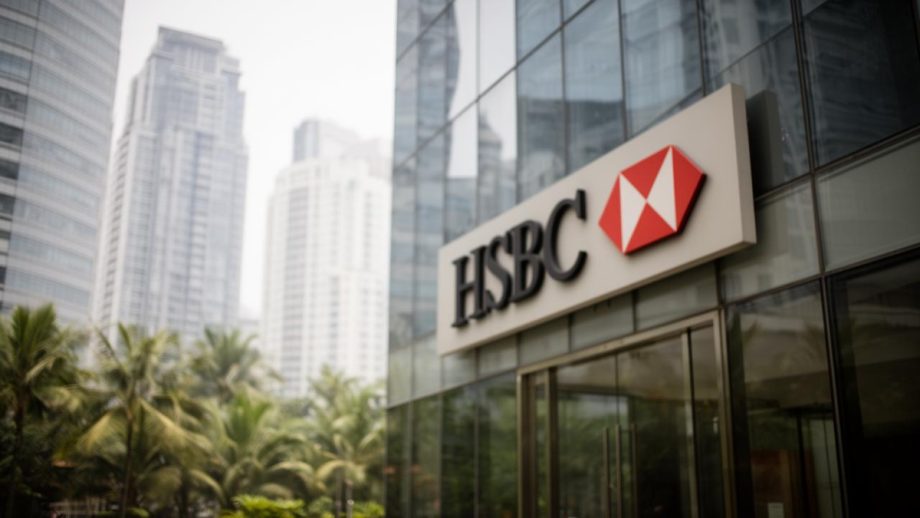
HSBC Holdings Plc has been weighing ways to reduce its dependence on China, Hong Kong included, and hand its Singapore operations more independence, according to people familiar with the matter, as the London-based lender looks to spread risk across its Asian franchise.
The internal review, carried out under the name “Project Sirena,” has examined several options for giving the Singapore arm greater autonomy, the people said, asking not to be identified discussing a private matter. The bank booked roughly 40% of its first-half pretax profit in Hong Kong.
The work puts HSBC alongside other large financial groups that are trying to shield their Asian assets from rising geopolitical tension. Singapore, helped by relative political stability and its status as a leading wealth and banking center, has emerged as a prime beneficiary as companies look beyond Greater China for operational flexibility.
As a first step, the bank intends to fold its main banking services in Singapore into a single entity over the next few years. A possible follow-on move would place other regional operations under that Singapore subsidiary, with the eventual aim of creating a second regional base alongside Hong Kong, the people said.
Surendra Rosha, co-CEO of Asia and the Middle East, confirmed in a statement that HSBC will combine its separate Singapore units as part of a simplification drive, while saying the bank has no plans beyond that. “All of our Asia-Pacific banking entities remain under the ownership and management of the Hongkong and Shanghai Banking Corp Limited subsidiary head office in Hong Kong, and there is no plan to make any changes to this,” he said in an emailed statement.
HSBC has also recently faced intense scrutiny from Hong Kong authorities over its allocation of artificial intelligence talent to Singapore, as both Asian financial hubs compete for dominance. The lender currently runs a hybrid structure in jurisdictions such as Singapore. In May 2016, it locally incorporated its retail banking and wealth management business in Singapore under HSBC Bank (Singapore) Ltd, while also operating a branch under Hong Kong. It runs locally incorporated subsidiaries in countries such as Malaysia and Indonesia, though both remain under its Hong Kong-based business.
A subsidiary is more free-standing than a branch, with its own governance, capital needs and deeper local regulatory oversight, and it faces different treatment in the event of financial difficulties.
The lender has radically overhauled its business over the past couple of years since Georges Elhedery became chief executive in September 2024. Under his leadership the bank has shuttered, sold or merged several business lines and cut thousands of jobs as it refocuses on core Asian markets. Elhedery has made stripping complexity out of HSBC a central plank of the overhaul, saying earlier this year that he had been “ruthless about killing complexity” at the lender.
Hong Kong remains HSBC’s profit engine, generating US$7.8 billion of pretax profit in the first half of fiscal 2026, about 40% of the group total. Singapore, despite its growing importance as an Asian wealth hub, contributed just US$774 million, roughly a tenth of Hong Kong’s figure. India added US$965 million and mainland China US$1.8 billion, according to HSBC’s accounts.
| Market | First-half 2026 pretax profit | Share of group total |
|---|---|---|
| Hong Kong | US$7.8 billion | About 40% |
| Mainland China | US$1.8 billion | – |
| India | US$965 million | – |
| Singapore | US$774 million | – |
Note: Figures are from HSBC’s accounts for the first half of fiscal 2026. Shares for mainland China, India and Singapore were not disclosed in the source material.
The concentration of earnings in Hong Kong explains why the review is being handled with care. HSBC’s dual role as a note-issuing bank in the territory and a major lender on the mainland means any restructuring that looks like a retreat could carry political and regulatory costs, even as the bank seeks the operational flexibility that a stronger Singapore subsidiary would provide.
For investors, the signal is that Asia’s largest lender is preparing contingency options rather than announcing a strategic shift. The confirmation of a Singapore entity merger is concrete; the broader idea of a second regional base remains an internal discussion subject to change. How far the bank proceeds will depend on how quickly geopolitical risk rises and whether regulators in Beijing and Hong Kong signal tolerance for a more balanced footprint.
Read Full Article At Source