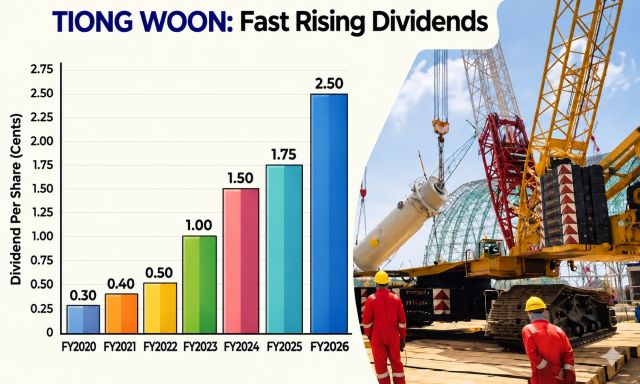
|
• CGS International now identifies another potentially higher-value opportunity: Singapore’s new power-generation build-out.
• It estimates three new gas-fired plants could generate roughly S$3 billion of construction demand over 2027–28. • These projects require moving and installing very heavy turbines, generators, cooling systems and storage tanks—exactly the type of high-tonnage work where Tiong Woon is strongest.
|
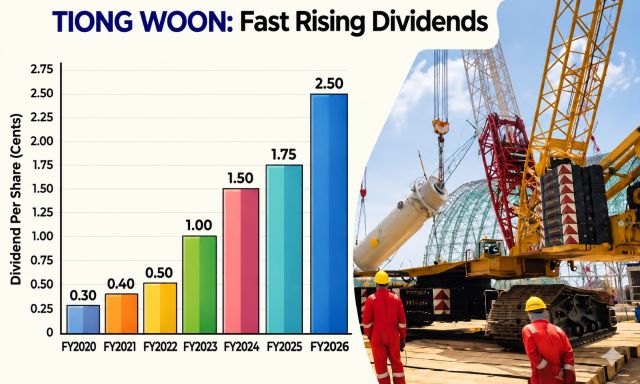
Excerpts from CGS Interntional report
Analysts: Natalie ONG and THEN Wan Lin
Tiong Woon Corp
| An indirect beneficiary of secular trends |
The recent Middle East tensions have shone the spotlight on energy security again.
Compounded by the rising electricity demands fuelled by secular AI industries (data centres and semiconductors) and push towards electric vehicles, Singapore launched another Request for Proposal (RFP) for new generation capacity in Apr 26, with one plant targeted to be operationally ready by 2031F, and another two plants to be ready by 2032F, equivalent to c.S$3bn in additional construction demand for 2027F-28F based on our estimates.
This not only increases TWC’s potential project pool, but also re-emphasises that TWC, due to its ability to participate in all construction subsectors, could be an indirect beneficiary of secular trends.
TWC ranks 15 on the 2025 IC100 rankings and its competitive advantage lies in the high tonnage and complex lift segment.
Petrochemical and oil and gas (O&G) projects command the highest revenues due to high tonnage lifting, while data centre and semiconductor projects require significant equipment; albeit overall tonnage of equipment rented is usually lower compared to petrochemical/O&G projects.
Singapore is TWC’s largest market, accounting for 73-78% of its total revenue over the last eight years.
 Natalie Ong, analystWe believe that Singapore is at the beginning of a multi-year construction upcycle.
Given TWC’s strategy to sell more value-added integrated lift services instead of equipment rental, we estimate TWC’s Singapore heavy lift and haulage revenue will grow 12%/7% yoy in FY27F/28F, outpacing industry progress payment growth of 7%/1% yoy.
Integrated work carries greater operational complexity and includes value-added services such as engineering, project management, haulage and installation services, allowing TWC to charge more compared to equipment rentals.
Read Full Article At Source