What happened?
Singapore stocks pulled back in September after a strong rally so far this year.
The Straits Times Index (STI) ended the month 1.4% lower after reaching a record high earlier in the month. Only five stocks had positive returns in September.
The Fed’s first interest-rate hike since 2023 brought renewed attention to how higher borrowing costs could affect Singapore blue chip stocks like DBS, OCBC and UOB, as well as interest rate sectors like Singapore REITs.
Against this volatile backdrop, Yangzijiang Shipbuilding, UOB and OCBC emerged as September’s best-performing blue chip stocks.
Notably, Yangzijiang Shipbuilding and OCBC were also among August’s three best-performing blue chips and July’s three best-performing blue chips, making them repeat appearances on the list.
In this article, we look at what drove the gains in September’s top gainers, how they fare under Beansprout’s Opportunity Pot screening framework and what investors may want to watch next.
3 best-performing Singapore blue-chip stocks in September 2026
| Rank | Stock | SGX code | September total return |
| 1 | Yangzijiang Shipbuilding | BS6 | 6.00% |
| 2 | UOB | U11 | 3.10% |
| 3 | OCBC | O39 | 1.50% |
| Source: SGX | |||
#1 – Yangzijiang Shipbuilding (SGX: BS6)
Yangzijiang Shipbuilding topped the list with a 6.0% total return in September.
This followed its strong August performance, when its share price rose 23.5%.
Yangzijiang Shipbuilding is one of China’s largest privately owned shipbuilders.
Its latest reported earnings provide useful context for the continued interest in the stock, although these results were released in August.
For the first half of 2026, revenue rose 36.2% year on year to RMB17.5 billion, while net profit increased 28.4% to RMB5.4 billion.
Higher-priced vessel contracts and a favourable mix of ships supported the results. Its shipbuilding gross profit margin reached 37.1%, compared with 35.2% a year earlier.
The company also had an order book of US$22.4 billion across 256 vessels at the end of June, with deliveries extending through 2030. Its net cash position stood at approximately RMB12.5 billion.
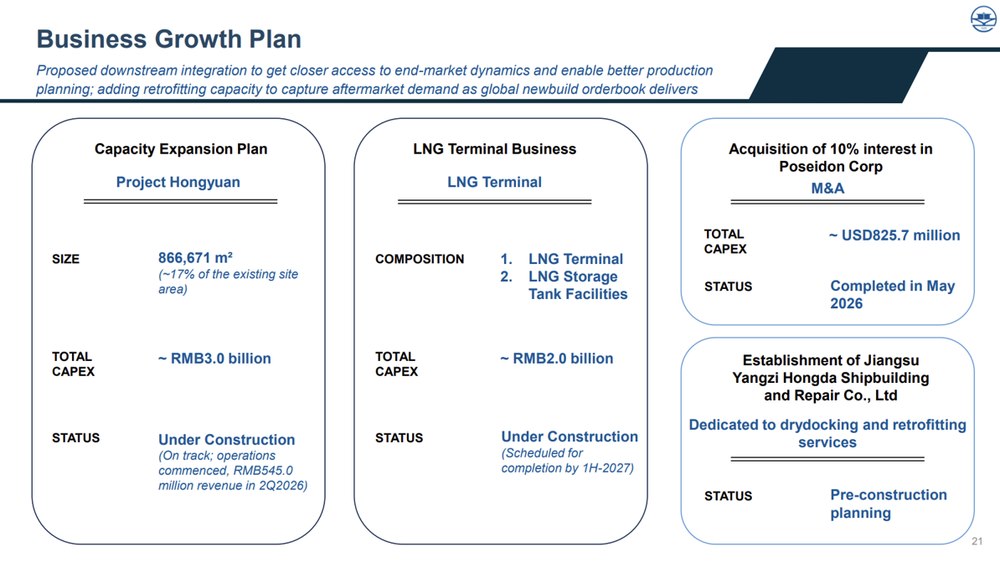
Yangzijiang is also investing to expand beyond its existing shipbuilding capacity.
Project Hongyuan has begun operations, while the group is also developing an LNG terminal and planning a repair and retrofitting business.
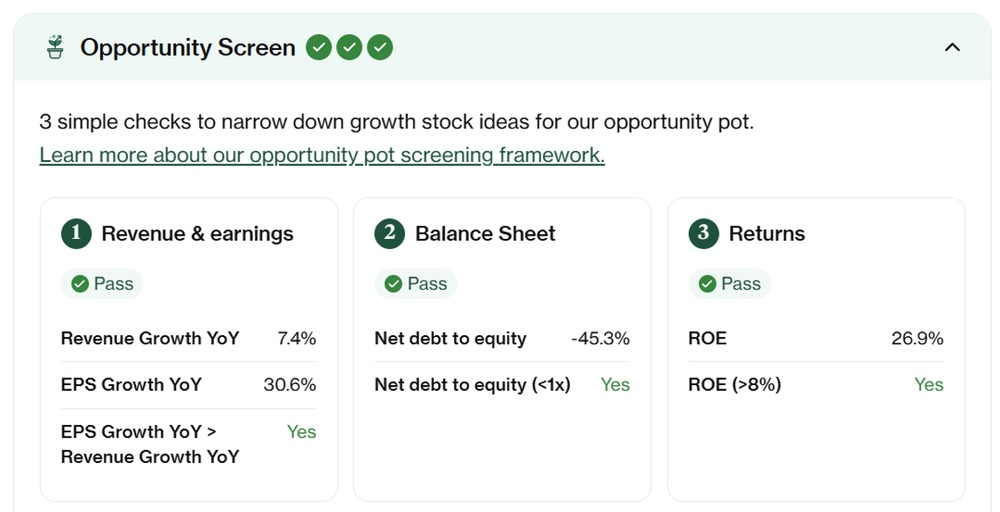
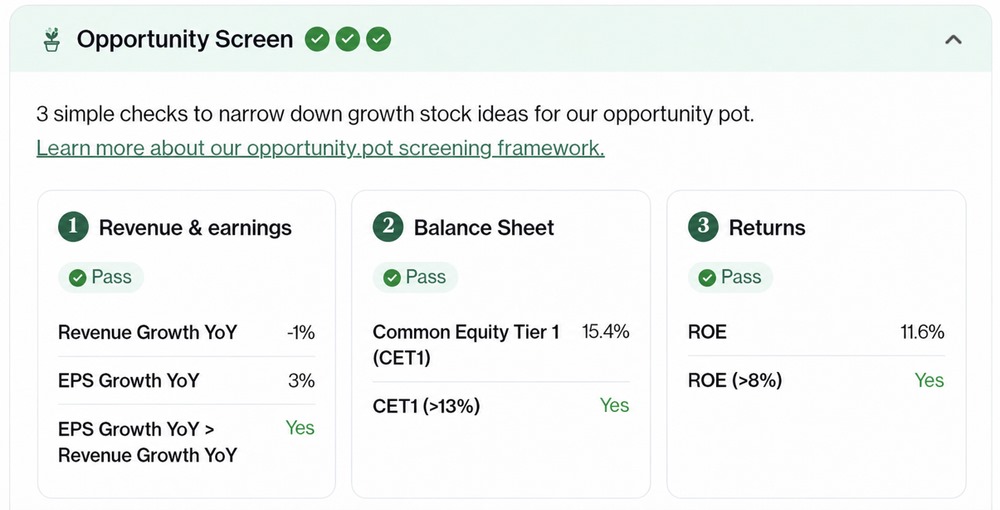
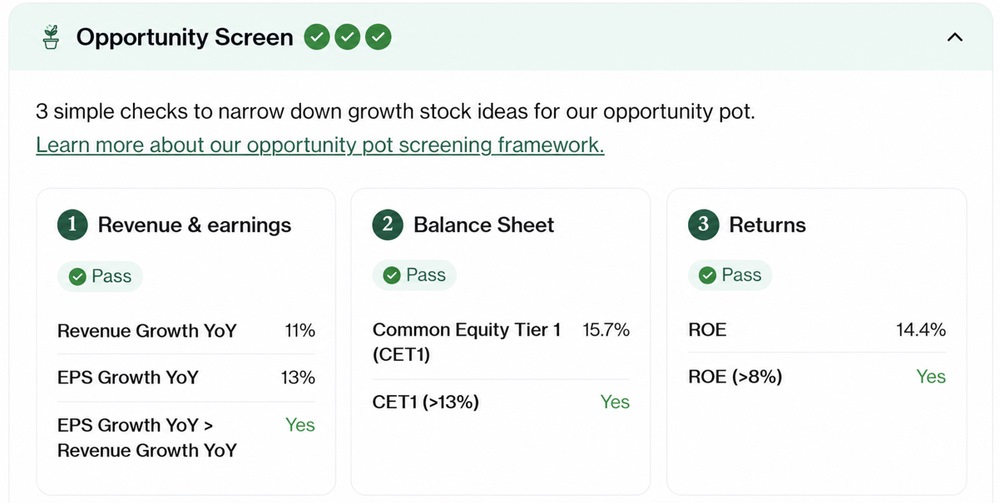
Yangzijiang Shipbuilding meets all three checks on Beansprout’s current Opportunity Screen.
Revenue increased 7.4%, while earnings per share grew 29.4%, satisfying the revenue and earnings check.
Its 26.9% return on equity meets the returns check, and net debt to equity of -45.3% meets the balance-sheet check.
The key question to answer is how much of this earnings strength can be sustained.
A large order book provides visibility, but I would still examine whether new contracts can replenish completed orders at attractive margins.
I would also watch delivery execution and cash generation as the company expands production.
After consecutive months of gains, I would compare the valuation with earnings across the shipbuilding cycle, including a scenario where margins become less favourable.
Related links:
Read Full Article At Source

